

Comparing 401(k)s, Traditional IRAs, Roth IRAs, SEP IRAs, and Other Tax-Advantaged Retirement Accounts
Choosing a retirement account is less about finding one universally “best” option and more about understanding how different accounts fit different employment situations, tax circumstances, and saving goals. A 401(k) offered through an employer works differently from an IRA opened independently, while a SEP IRA is designed around an employer contribution structure that can be particularly relevant to self-employed workers and small-business owners. Roth and traditional accounts add another layer because they place the primary tax benefit at different points in the saving and withdrawal process.
The differences become more important as balances grow and retirement approaches. Contribution limits, income restrictions, employer matching, tax treatment, required distributions, and investment choices can all affect how useful an account becomes over time. Rather than treating these accounts as competing products, it is more useful to view them as different pieces of a retirement system. The right combination depends on which accounts are actually available, how contributions are taxed, and how much flexibility an investor may need later.
2026 update: Contribution limits and other retirement-account rules can change from year to year. The figures discussed below reflect 2026 federal limits and rules available at the time of publication. Readers should verify current IRS guidance before making tax or retirement decisions.
Start With the Two Basic Tax Structures
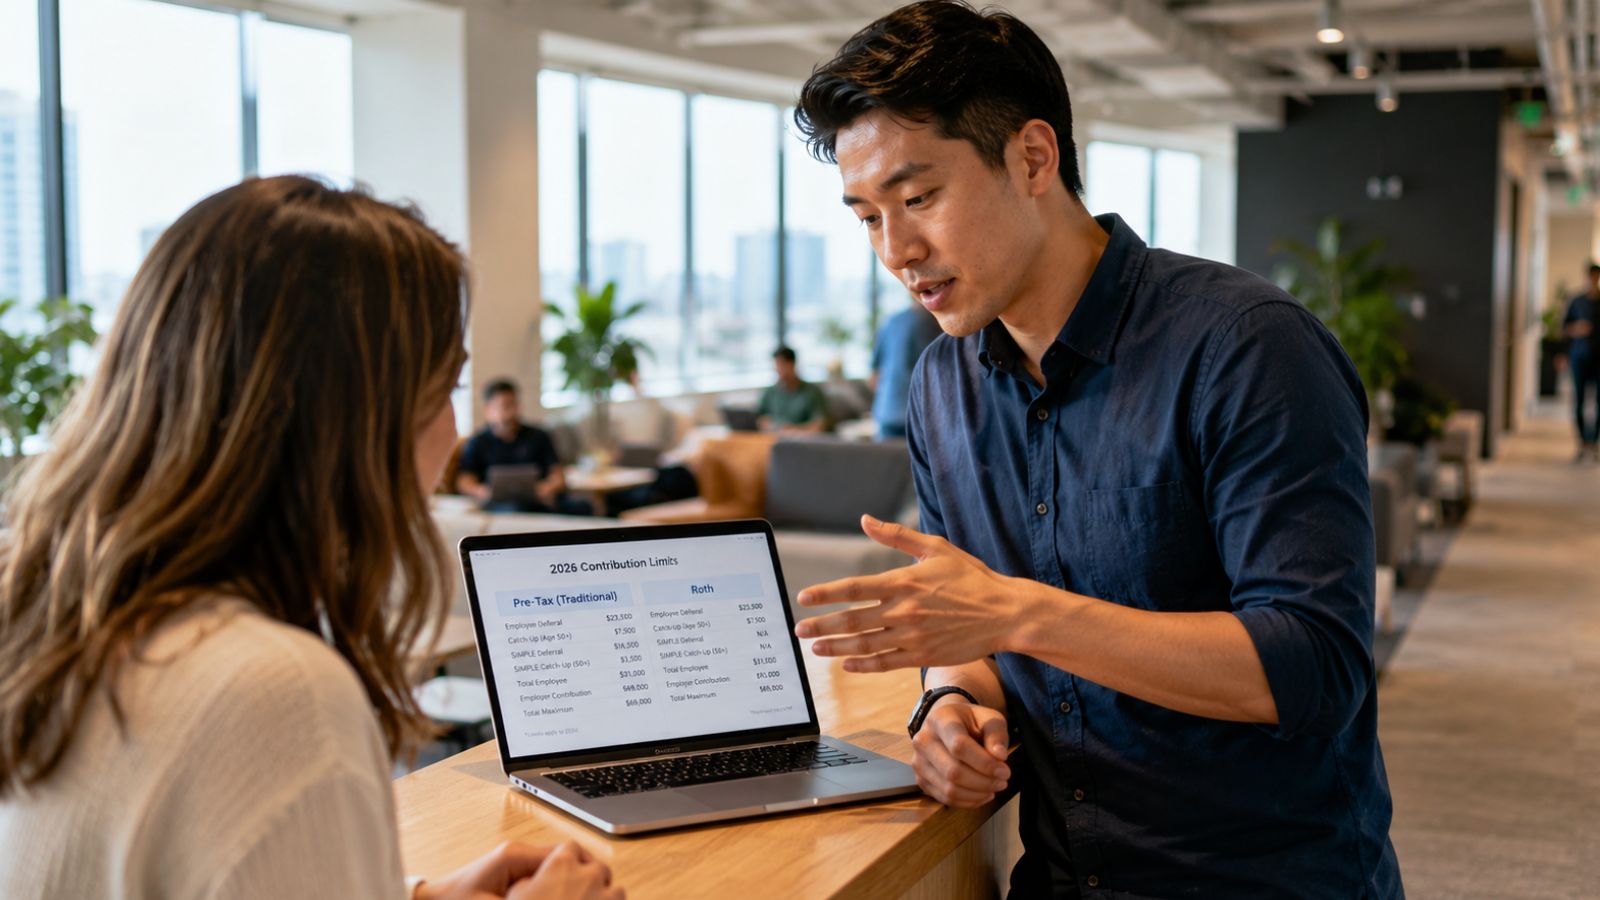
Most of the accounts discussed here can be understood by starting with a basic distinction: whether the primary tax benefit occurs before the money enters the account or after it has already been taxed. Traditional 401(k)s and traditional IRAs generally use a tax-deferred structure. Contributions may receive a tax benefit when made, depending on the account and the individual's circumstances, while investment earnings generally accumulate without current federal income tax. Withdrawals are generally taxable under the applicable rules. Roth accounts reverse much of that timing. Contributions are made with after-tax money, but qualified Roth distributions can generally be received tax-free. The difference is therefore less about whether one structure is “taxed” and more about when taxation occurs and what conditions apply when money eventually comes out.
That timing can matter because a person's tax situation may change substantially over a career. Someone in a relatively high tax bracket today may value a current deduction from a traditional account, while someone expecting higher taxable income later may place greater value on building Roth assets. There is no universal rule that one treatment will always produce a better result because future tax rates, income, contribution amounts, investment returns, and withdrawal patterns are uncertain. Roth and traditional accounts can also be used together, creating tax diversification rather than forcing every retirement dollar into one tax treatment. The important distinction is to understand the rules before comparing the accounts themselves.
401(k)s: The Main Workplace Retirement Option
For employees whose employers offer them, 401(k) plans can provide one of the largest annual opportunities for retirement contributions. In 2026, the basic employee elective-deferral limit for most 401(k) plans is $24,500. Participants who are at least 50 by the end of the year may generally make an additional $8,000 catch-up contribution if the plan permits it. For employees who turn 60, 61, 62, or 63 during 2026, the higher catch-up limit is $11,250 instead. The overall defined-contribution plan limit for 2026 is $72,000, before considering applicable catch-up contributions. These figures apply within specific federal rules, and an employer's plan can impose additional limitations on what an individual participant is permitted to contribute.
A workplace plan can also have a feature that an individual IRA cannot replicate: employer contributions. Matching contributions can add retirement assets without requiring the employee to contribute the same amount personally, although the exact formula, vesting schedule, and eligibility requirements depend on the plan. Investment choices are also determined by the employer's plan menu rather than by the participant's access to the entire brokerage market. Many plans now offer both traditional and Roth contribution options, allowing participants to choose between current tax treatment and potential tax-free qualified distributions later. Beginning in 2026, certain higher-paid participants who are eligible for catch-up contributions must make those catch-up contributions on a Roth basis when their prior-year wages from the plan sponsor exceed $150,000, subject to the applicable rules.
Traditional IRAs: Flexible, but Tax Benefits Depend on Circumstances
A traditional IRA provides an individually owned retirement account that can supplement an employer plan or serve as a primary retirement account for someone without workplace coverage. For 2026, the combined annual contribution limit across an individual's traditional and Roth IRAs is $7,500, or $8,600 for someone age 50 or older, subject to the taxable-compensation limit. The important point is that contributing to a traditional IRA and deducting the contribution are separate questions. A person may be eligible to make a contribution but receive only a partial deduction or no deduction, depending on income, filing status, and whether the individual or spouse is covered by a workplace retirement plan.
This distinction makes traditional IRAs less straightforward than their basic description suggests. For example, the deduction phase-outs for 2026 vary substantially depending on filing status and workplace-plan coverage. Someone covered by a workplace plan may face an income-based reduction in the deductible amount, while different rules apply when only a spouse is covered. The account also generally falls under required minimum distribution rules applicable to traditional IRAs, meaning retirement planning eventually has to account for taxable withdrawals under federal rules. A traditional IRA can therefore provide valuable tax-deferred growth and potentially deductible contributions, but its usefulness depends heavily on the investor's specific tax circumstances rather than simply on the fact that it is an IRA.
Roth IRAs: Tax-Free Qualified Withdrawals With Income Limits
Roth IRAs use a different tax structure from traditional IRAs. Contributions are made with after-tax dollars, so there is generally no federal income-tax deduction for the contribution itself. The potential benefit comes later: qualified distributions can generally be taken without federal income tax, and original Roth IRA owners are not subject to lifetime required minimum distributions under the current rules. That combination can make Roth assets useful as part of a broader retirement plan because they provide a pool of assets whose withdrawals can have different tax characteristics from withdrawals from traditional retirement accounts. The trade-off is that direct Roth IRA contributions are subject to income-based eligibility limits.
For 2026, the Roth IRA contribution limit shares the $7,500 annual limit with traditional IRAs, with an $8,600 catch-up limit for individuals age 50 and older. However, the ability to make a direct Roth IRA contribution phases out at higher modified adjusted gross income levels. For single filers and heads of household, the 2026 phase-out range is $153,000 to $168,000; for married couples filing jointly, it is $242,000 to $252,000. Separate rules apply to married individuals filing separately. These thresholds are particularly important because the Roth IRA limit is a combined IRA contribution limit, not a separate $7,500 allowance on top of a traditional IRA contribution. Someone contributing to both accounts must generally stay within the applicable combined annual limit.
SEP IRAs and Other Options for Self-Employed Workers
SEP IRAs are structured differently from traditional and Roth IRAs because they are primarily an employer-funded retirement arrangement. They can be relevant to self-employed individuals, sole proprietors, and small-business owners who want the ability to make larger contributions than the standard IRA limit allows. For 2026, an employer's SEP contribution for an employee generally cannot exceed the lesser of 25% of compensation or $72,000, subject to the rules governing compensation and eligible employees. Unlike a standard 401(k), SEP plans generally do not permit elective salary-deferral contributions or catch-up contributions. That difference is important because the contribution calculation and funding mechanism depend on business compensation rather than simply on the individual's decision to defer part of a paycheck.
SEP IRAs are also different from Roth IRAs in their tax structure and from ordinary individual IRAs in their employer responsibilities. When a business establishes a SEP, contributions generally must follow the plan's eligibility and contribution requirements for qualifying employees rather than being available solely to the business owner. Other self-employed and small-business options may provide different mechanics. For example, SIMPLE IRA plans have their own employee contribution limits and employer contribution requirements, while a solo 401(k) can provide a different combination of employee deferrals and employer contributions for an eligible owner. These alternatives matter because the best account structure for a self-employed person depends not only on income level, but also on whether there are employees, how contributions are calculated, and how much administrative complexity the business is prepared to handle.
How the Accounts Differ in Real-World Use
The practical difference between retirement accounts becomes clearer when viewed through the circumstances that determine access to them. An employee with a workplace 401(k) may have access to employer matching contributions and substantially higher annual employee-deferral limits than an IRA provides. An investor without a workplace plan may rely more heavily on an IRA, while someone who is self-employed may have additional choices such as a SEP IRA, SIMPLE IRA, or an individual 401(k), depending on the business structure and eligibility requirements. Investment flexibility can also differ. An IRA opened at a brokerage can generally offer a broad range of investments, whereas a 401(k) participant is normally limited to the options selected by the plan sponsor.
Tax treatment is another major dividing line, but it should not be evaluated separately from account availability. Traditional and Roth versions can sometimes exist within the same workplace plan, while direct Roth IRA contributions are subject to income limits. Traditional IRA deductions can also be limited by income and workplace-plan coverage, even when a contribution itself is permitted. Meanwhile, employer-funded arrangements such as SEP IRAs operate under a different set of contribution mechanics. These distinctions mean that account selection is rarely just a question of comparing percentages or contribution limits. It is a process of matching the account's rules to the person's employment status, income, tax circumstances, and intended retirement timeline.
Building a Combination Instead of Choosing Just One Account
Many retirement savers eventually use more than one account because different accounts solve different planning problems. An employee might contribute to a workplace 401(k), receive available employer contributions, and also use an IRA if eligible. Someone with a self-employment business might use a SEP IRA or another small-business retirement arrangement while maintaining an IRA for additional tax diversification. The objective is not necessarily to accumulate money in as many accounts as possible. Instead, multiple accounts can create different sources of retirement assets with different tax characteristics, contribution rules, and withdrawal considerations.
This approach can also create flexibility when retirement arrives. A retiree with only traditional tax-deferred assets may face a different taxable-income profile from someone who has a mixture of traditional, Roth, and taxable investments. Roth assets can potentially provide tax-free qualified distributions, while traditional accounts can provide tax-deferred accumulation followed by taxable withdrawals. The relative usefulness of each account depends on the rules in effect, the investor's tax situation, and how retirement income is ultimately generated. Because tax laws and contribution limits change periodically, a strategy that made sense several years ago may need to be reassessed rather than carried forward automatically.
The Most Important Questions to Ask Before Choosing an Account
The first question is usually not “Which retirement account is best?” but “Which accounts can I actually use?” Employment status, employer-plan availability, income, filing status, compensation, and business structure determine the realistic set of choices. Once that is established, the next questions concern tax treatment, contribution limits, employer contributions, investment choices, and future withdrawal rules. This sequence prevents a common mistake: comparing two accounts as though both were equally available when one may be subject to income restrictions or employer-plan requirements.
The final consideration is how the account fits into the rest of the retirement system. A retirement account is only a container; the investment choices inside it, the amount contributed, the time invested, and the eventual withdrawal strategy all influence the outcome. A high contribution limit does not automatically make an account appropriate, just as tax-free qualified withdrawals do not make a Roth account universally superior to a traditional account. For that reason, retirement-account decisions are better evaluated as part of a broader plan rather than as isolated product comparisons. Federal rules can also change, so current IRS guidance should be checked before relying on specific contribution limits, eligibility thresholds, or tax provisions.
Conclusion
401(k)s, traditional IRAs, Roth IRAs, SEP IRAs, and other retirement arrangements are built around different combinations of tax treatment, contribution rules, employment requirements, and withdrawal considerations. A 401(k) can provide substantial contribution capacity and potential employer contributions, while traditional and Roth IRAs provide individually controlled accounts with different tax characteristics. SEP IRAs and other small-business plans address a different set of needs by allowing retirement contributions to be structured around self-employment or business compensation.
The most useful way to compare these accounts is therefore not to search for a single winner. It is to identify which accounts are available, understand where their tax benefits occur, examine their contribution and eligibility rules, and then consider how they can work together over a multi-decade retirement timeline. The specific figures cited here reflect 2026 federal rules and should be treated as time-sensitive information rather than permanent limits. Before acting on a retirement or tax strategy, readers should verify the applicable IRS rules and consider their own circumstances or seek advice from an appropriately qualified financial or tax professional.
Filed under
More Stories


