How Credit Reports, Credit Scores, and Credit Histories Shape Modern Lending Decisions
Applying for a mortgage, auto loan, or credit card in the United States usually involves more than simply filling out an application. Behind each lending decision is a data-based system that helps financial institutions evaluate risk.
Three important components work together in this process: credit histories, credit reports, and credit scores. Although these terms are often used interchangeably, they represent different parts of the consumer credit system.
Understanding how they connect can help consumers better understand why lenders review credit information and how financial decisions are made.
Credit History: The Foundation of Credit Information
A credit history is the record of a person’s past credit-related activities over time. It is not a document or a single number, but a collection of financial behaviors.
Activities such as opening credit accounts, making loan payments, applying for new credit, or having certain accounts reported to collections may become part of a consumer’s credit history.
This information is typically provided by lenders and financial institutions to consumer reporting agencies (CRAs), commonly known as credit bureaus.
Credit Reports: Organizing Financial Records
A credit report is a detailed record created by a credit bureau based on available credit history information. Companies such as Equifax, Experian, and TransUnion compile these records for use by authorized organizations.
A typical credit report includes several categories:
Personal information:
Basic identifying details, such as name, addresses, and other information used for record matching.
Credit accounts:
Information about open and closed accounts, including balances, account history, payment records, and credit limits.
Credit inquiries:
Records showing when organizations request access to credit information. These may include hard inquiries related to applications and soft inquiries related to monitoring or reviews.
Collections and public records:
Certain negative financial events, such as accounts sent to collections, may also appear depending on reporting rules.
Credit Scores: Turning Data Into a Risk Indicator
A credit score converts information from a credit report into a three-digit number using statistical models.
Scoring systems such as FICO and VantageScore analyze factors including:
Payment history
Credit utilization
Length of credit history
Types of credit accounts
Recent credit applications
The purpose of a credit score is not to judge a person’s character. Instead, it helps lenders estimate the likelihood of future repayment problems based on historical patterns.
How Lenders Use Credit Information
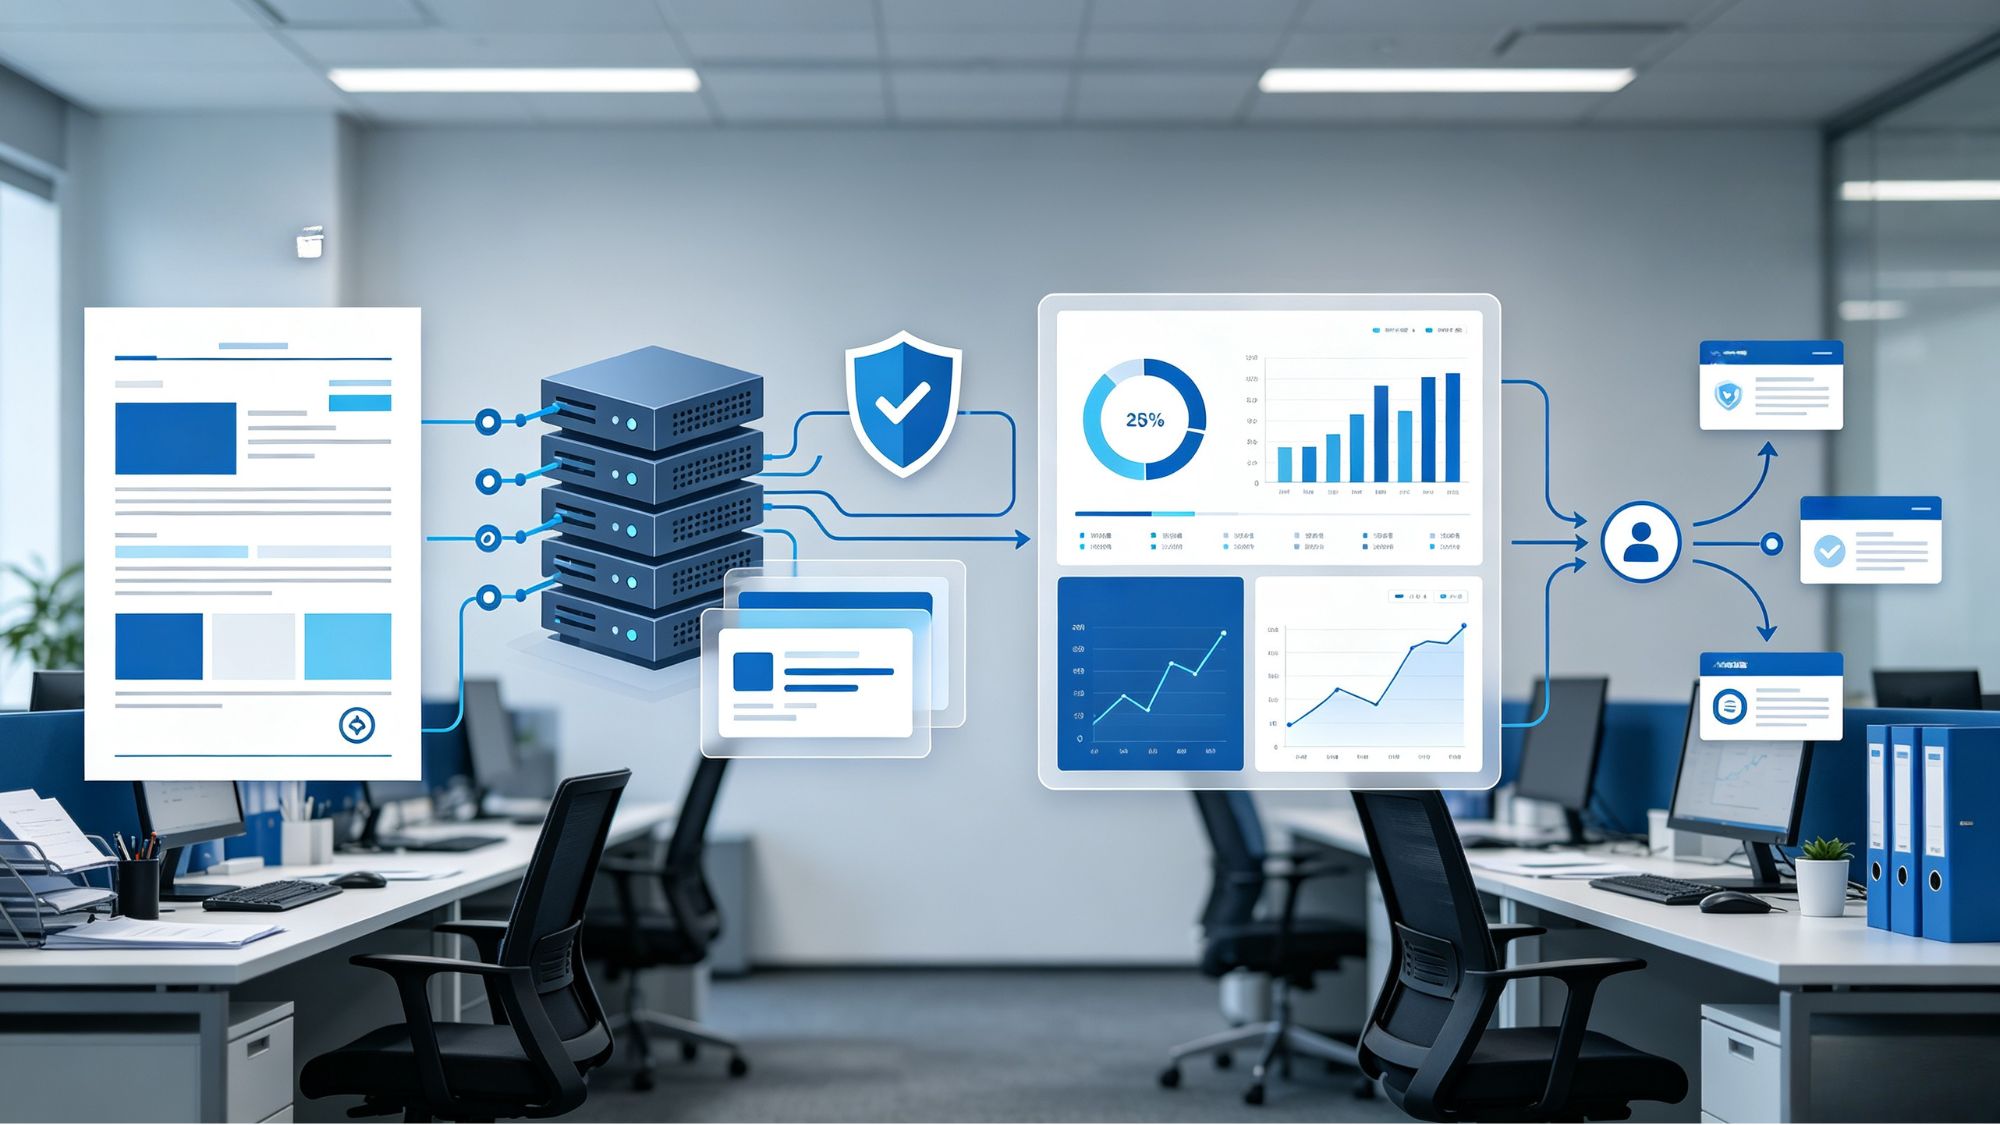
When someone applies for credit, lenders usually collect information from one or more credit bureaus. Because different companies may report information differently, credit reports from different bureaus may not always be identical.
After reviewing the available data, automated underwriting systems may calculate risk levels and help determine whether additional review is needed.
For example, two borrowers may both have a credit score of 720, but their profiles may look different. One person may have a long history of managing several types of accounts, while another may have a shorter history based mainly on one credit card.
Because of these differences, lenders often consider additional factors such as income stability, existing debt obligations, and debt-to-income ratio.
Consumer Rights and Credit Accuracy
Because credit information can influence access to loans and financial products, consumers have rights regarding their credit records.
Under the Fair Credit Reporting Act (FCRA), consumers can review their credit reports and dispute inaccurate information. Errors such as incorrect account information or outdated records may affect credit evaluations.
Correcting inaccurate information may improve the accuracy of a credit profile and could influence future lending decisions.
Conclusion
Credit histories, credit reports, and credit scores work together as different parts of the modern lending system. Credit history provides the underlying record of financial activity, credit reports organize that information, and credit scores summarize risk factors using statistical models.
Understanding this relationship helps consumers better manage their financial information and understand how lenders evaluate credit applications.
Filed under
More Stories